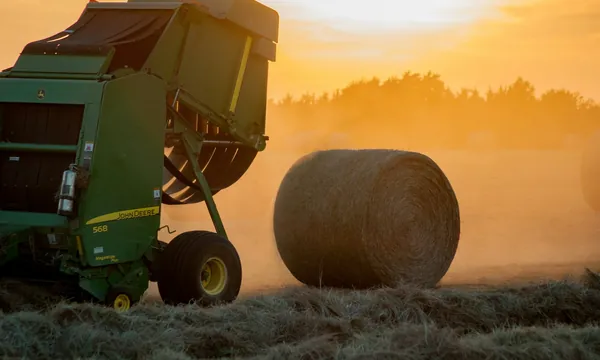
Illustrative licensed U.S. photography · Photo credits
FLORIDA · 2026 GUIDEA farm-equipment tax exemption
What It Does
Exempts eligible tangible personal property used in agricultural production or agritourism on agricultural-classified land. The property must belong to the landowner or leaseholder. Starts with the 2027 tax year.
This concerns tangible personal property, such as qualifying equipment. It does not exempt all agricultural land, all business property, or every item used by a contractor.
Potential Effects
Possible Benefits
Reduces qualifying farm operating costs and could support agricultural investment.
Potential Trade-Offs
Local governments lose revenue. Similar nonfarm businesses do not receive this specific exemption.
A Yes Vote
Approve the exemption for qualifying agricultural equipment and other tangible property.
A No Vote
Keep existing tax treatment for that property.
Potential effects are analysis, not guaranteed household outcomes. The interactive guide retains the full income and scenario breakdown where evidence is available.